
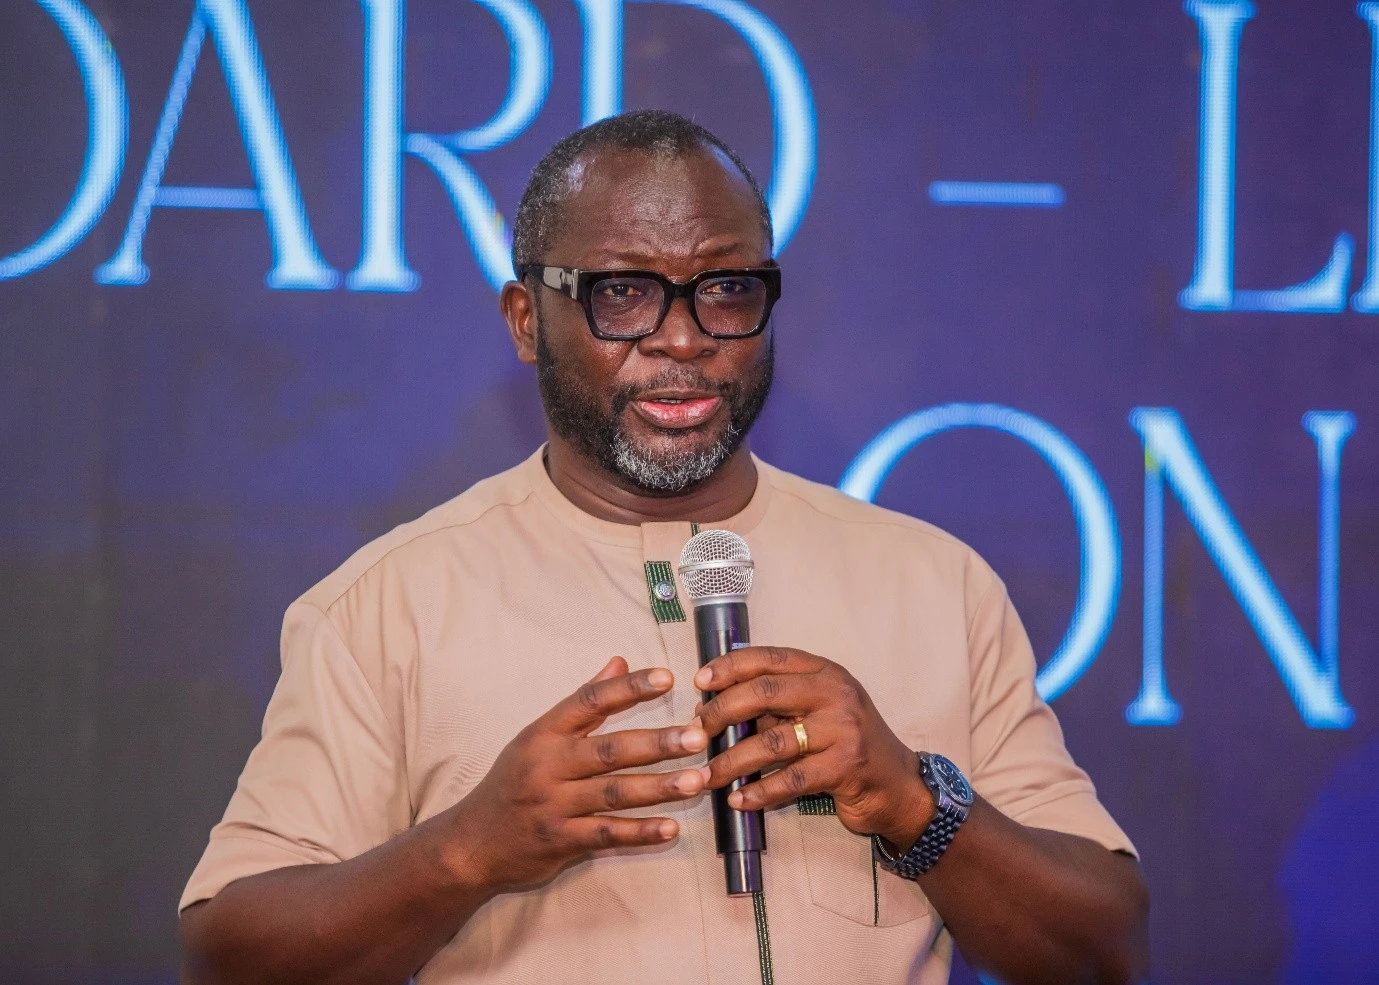
The Ghana Association of Banks (GAB) says efforts to increase lending to small and medium-sized enterprises (SMEs) must be accompanied by stronger systems to reduce the risks facing businesses and lenders. President of the Association, John Awuah, said banks are willing to provide more financing to SMEs, but weaknesses in areas such as storage, distribution and market access can undermine borrowers’ ability to repay loans.
Speaking during a roundtable discussion at the Chartered Institute of Bankers Ghana (CIB Ghana) Post-MPC Policy Seminar, GAB President, John Awuah said the focus should therefore go beyond simply directing banks to increase lending to SMEs and instead address the broader risks within the business environment. “Before we start talking about lending to SMEs, we need to ensure that the credit chain is properly enclosed,” Mr Awuah said.
He cited agriculture as an example, noting that farmers can obtain financing, increase production and still struggle to repay their loans if there are inadequate systems to store and market their produce. “We saw tomatoes, heaps of them by the roadside. That, you know, they said, locked in the farm gates, glut. And for that reason, farmers were losing money,” he said.
According to Mr Awuah, this creates a situation where a bank can provide financing for increased production, only for the resulting produce to go to waste, leaving the borrower unable to repay. “You cannot have a situation where a bank gives a farmer one million Ghana cedis… all of a sudden can do 10 acres. And that’s10 acres and the farm produce gets rotten. And then there’s default,” he said.
He argued that Ghana must therefore work to de-risk the SME environment by strengthening the systems that connect production, storage, distribution and markets. “We need to improve the risk profile, not of the SME, but in the systemic profile of the risk,” Mr Awuah said.
He also raised concerns about the effectiveness of some mechanisms intended to support agricultural financing, including the commodity exchange and warehouse receipt systems. “We have commodity exchange, which to me, for all intents and purposes, is dysfunctional. Warehouse receipts don’t work in this country,” he said.
NPL risk remains a major concern
Mr Awuah’s comments come amid efforts to reduce the banking sector’s non-performing loan (NPL) ratio while expanding credit to the economy. He cautioned that the decline in the NPL ratio should not automatically be interpreted as an improvement in borrowers’ repayment behaviour.
According to him, the ratio could fall simply because the overall loan book is expanding faster than the stock of non-performing loans. He said banks and policymakers therefore need to examine whether the underlying credit performance of borrowers is actually improving.
“The question we should be asking is, does it necessarily mean that repayment culture or credit performance culture has improved?” he said. Mr Awuah stressed that high NPLs pose a significant risk to banks because they can result in the loss of the principal amount lent, rather than merely the interest income expected from the loan.
“If two, just two of those loans go bad, you are not just losing the interest, you are losing the principal amount,” he said. He explained that this risk influences where banks deploy their liquidity, as lenders have to consider the likelihood that funds advanced to businesses will be repaid.
“It is not by design that banks channel their liquidity into a certain sector. There is a balance of risk,” he said.
GAB calls for stronger credit architecture
Mr Awuah also called for improvements in Ghana’s credit architecture to allow banks to better differentiate borrowers according to their credit histories and risk profiles.
He said stronger credit information would allow lenders to make more informed decisions about the amount of credit a borrower can access and the appropriate pricing of that credit.
The GAB President maintained that banks are already supporting SMEs through dedicated programmes, but said more can be done if the broader risk environment is improved.
“If you lose the fight on lending to the SME, we’ve lost the economic fight,” he said.
He noted that SMEs account for a significant share of businesses in Ghana, making access to sustainable financing critical to economic activity.
“Banks are lending to SMEs,” he said. “But all I’m saying is a lot more can be done to deepen interest in that.”
Source: Citinewsroom
